Are you living in the Bay State and wondering just how much it’ll cost to insure your set of wheels? You’re in the right place! Navigating the world of auto insurance in Massachusetts can feel like a maze, but fear not—we’re here to steer you in the right direction. From understanding baseline requirements to grasping what affects your premium, we’ve got the insights you need.
Auto insurance in Massachusetts isn’t just about meeting legal obligations; it’s about making sure you’re equipped with the right coverage that meets your lifestyle and budget. We’ll dive deep into the nitty-gritty of costs, factors influencing rates, and money-saving strategies, all with a clear, engaging approach reminiscent of Backlinko’s style.
Overview of Auto Insurance in Massachusetts
Did you know that driving without insurance in Massachusetts is not just risky but illegal? Yep, that’s right! You need to have a policy in place to hit the road here.
Massachusetts law requires every driver to carry a minimum amount of auto insurance. But what’s that exactly? Well, it includes bodily injury liability, property damage liability, and personal injury protection (PIP). But there’s more!
Understanding the Mandatory Insurance Requirements
So, you might be wondering, what are the specifics? Here’s the deal: Massachusetts mandates a minimum of $20,000 per person and $40,000 per accident for bodily injury coverage. Plus, $5,000 for property damage. And don’t forget, PIP coverage of up to $8,000 is also a must-have.
Types of Auto Insurance Coverage in Massachusetts
Beyond the basic requirements, there are several other coverage options available. You can get collision, comprehensive, and uninsured motorist coverage. Each comes with its own set of benefits. Comprehensive coverage protects against non-collision incidents, like theft or natural disasters.
- Collision Coverage: Pays for damage to your car after an accident.
- Comprehensive Coverage: Covers non-collision-related damages.
- Uninsured/Underinsured Motorist: Protects if the other party lacks adequate insurance.
Factors Influencing Auto Insurance Costs in Massachusetts
Now, let’s talk dollars and cents. Insurance costs can vary widely. So, what affects these costs in Massachusetts? Simple: your driving record, the type of car you drive, and even where you live. Yes, your ZIP code matters!
Here’s another interesting factor: age. Younger drivers often face higher premiums because they’re considered riskier. But don’t despair! There are ways to reduce costs.
Pro Tip: Installing anti-theft devices in your car can lead to discounts on your premium.
Step #1: Shop around! Different insurers offer different rates, so compare.
Step #2: Consider bundling insurance policies. Many companies offer discounts if you combine auto with home insurance.
Costs of Auto Insurance in Massachusetts
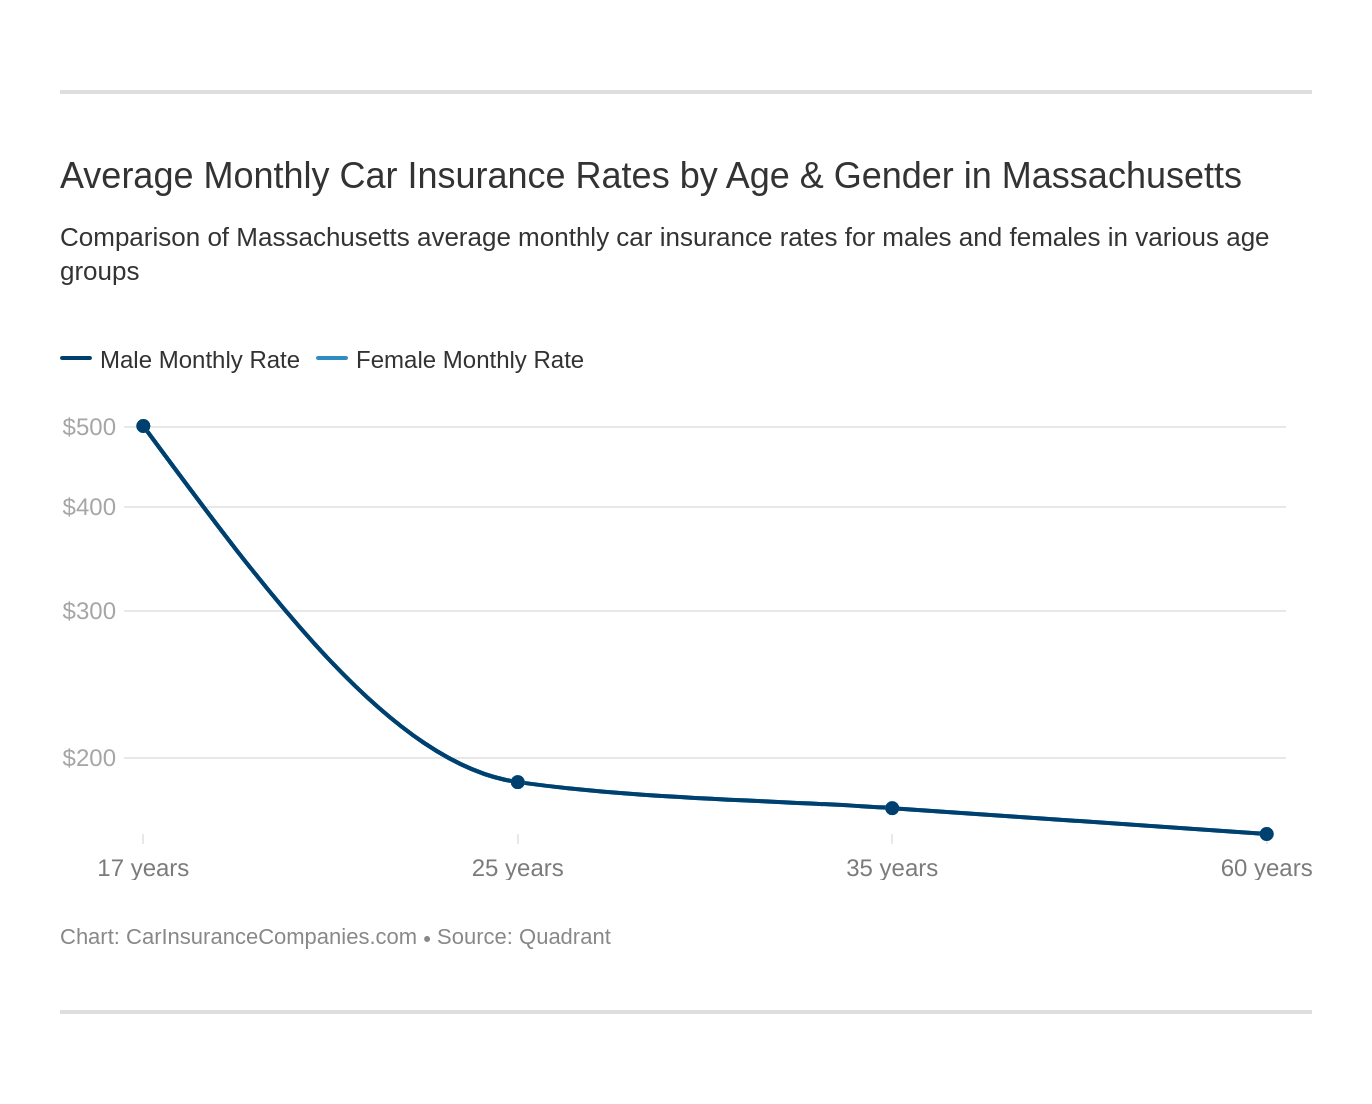
Did you know that Massachusetts is among the states with the highest auto insurance rates in the U.S.? It might seem daunting, BUT understanding the costs could save you a ton of money.
Let’s dig in. The average cost of auto insurance in Massachusetts is around $1,460 per year. That’s above the national average. But don’t let that scare you. There are ways to find affordable rates if you know where to look.
Comparing Insurance Providers in Massachusetts
Different insurance providers can have wildly different rates. Here’s the deal: it’s crucial to compare them side-by-side. Below is a table that breaks down average yearly premiums from some of the top insurers in Massachusetts.
| Insurance Provider | Average Annual Premium |
|---|---|
| Geico | $1,150 |
| Liberty Mutual | $1,480 |
| Progressive | $1,390 |
| State Farm | $1,450 |
See the variance? It pays to shop around!
Regional Variations in Costs Across Massachusetts
Here’s the truth: where you live in Massachusetts can significantly impact your insurance costs. Urban areas like Boston often have higher rates due to traffic congestion and accident rates. Meanwhile, rural areas might offer some relief.
For example, a driver in Boston might pay over $1,700 annually, whereas someone in a quieter town like Amherst could be looking at closer to $1,200. That’s a huge difference!
Pro Tip: Consider moving outside major urban hubs if you’re flexible and looking to save on auto insurance.
Factors Influencing Auto Insurance Rates
Did you know that two people with identical cars can pay vastly different insurance rates? It all boils down to a cocktail of factors that insurers consider before setting your premium.
In Massachusetts, auto insurance rates are influenced by a unique set of factors that can either make or break your budget. Let’s dive into what these are and how they can impact your wallet.
Driving History Matters
Your driving history is a major player in determining your insurance costs. If you’ve got a squeaky-clean record, you’re in luck! Insurers love safe drivers and reward them with lower rates. BUT, if you’ve had a few fender benders or speeding tickets, brace yourself for a rate hike. Why? Insurers see you as a bigger risk, and they charge you accordingly.
Here is the deal: a single speeding ticket can raise your rates by up to 20%. That’s no small change. So, next time you’re tempted to speed through a yellow light, think of the potential hit to your insurance premium.
The Impact of Vehicle Type and Usage
Believe it or not, the kind of car you drive plays a huge role in your insurance costs. Are you driving a sleek sports car or a reliable family sedan? Sports cars often come with higher premiums due to their speed capabilities and higher repair costs.
Usage also matters. If you’re using your vehicle for commuting long distances every day, expect to pay more. Why? More miles mean more risk. Insurers factor in your vehicle usage when calculating rates because the more you drive, the higher the chance you’ll be in an accident.
Pro Tip: Consider bundling your auto insurance with other policies, like home insurance, to score a bundle discount.
Discounts and Savings on Auto Insurance

Did you know that you could slash your auto insurance costs by up to 30%? It’s all about the discounts and savings opportunities you might be missing. Let’s dive into some of the most common ways you can save on auto insurance in Massachusetts.
Insurance companies love rewarding their clients with discounts. The trick is knowing where to look and how to qualify for them.
Common Discounts Available in Massachusetts
These discounts are the low-hanging fruit of auto insurance savings. If you qualify, you can lower your premiums significantly:
- Good Driver Discount: Maintain a clean driving record and save big.
- Multi-Vehicle Discount: Insure more than one car under the same policy.
- Good Student Discount: Students with a high GPA can benefit from reduced rates.
- Safety Features Discount: Own a vehicle with advanced safety features? Get a discount.
- Anti-theft Discount: Vehicles with anti-theft devices are cheaper to insure.
But here’s the deal: simply knowing about these discounts isn’t enough. You need to actively ask your insurer to apply them.
Bundling Policies for Maximum Savings
Want to save even more? Consider bundling your insurance policies. When you combine your auto insurance with other policies like home or renters insurance, most companies will offer a substantial discount.
This is how it works: Insurance companies value your loyalty. By giving them more business, they reward you with better rates. It’s a win-win!
Strategies to Lower Premiums Effectively
If you’re serious about cutting costs, follow these steps:
- Shop Around: Compare quotes from multiple insurers. Loyalty is great, but saving money is better.
- Increase Your Deductible: Opt for a higher deductible to reduce your premium.
- Improve Your Credit Score: Yes, your credit score can impact your insurance rates. Work on boosting it.
Pro Tip: “Review your policy annually. Circumstances change, and so do your insurance needs. Adjusting your coverage could lead to savings.”
By following these strategies, you’re not just a policyholder – you’re a savvy saver. Don’t leave money on the table!
Legal and Regulatory Aspects
Think you’re covered with just any auto insurance in Massachusetts? Think again. The state has some of the strictest requirements in the country.
If you’re planning to drive in Massachusetts, you need to know the legal requirements for auto insurance. Failing to meet these can result in heavy penalties. Let’s dive into what you absolutely must have to stay on the right side of the law.
Minimum Legal Requirements for Auto Insurance in Massachusetts
In Massachusetts, you can’t just have any old insurance policy. You must have coverage that meets the state’s minimum requirements. Here’s what you need:
- Bodily Injury to Others: A minimum of $20,000 per person and $40,000 per accident.
- Personal Injury Protection (PIP): Coverage of $8,000 per person.
- Bodily Injury Caused by an Uninsured Auto: $20,000 per person and $40,000 per accident.
- Damage to Someone Else’s Property: At least $5,000.
This is the bare minimum. If you think this might not be enough, you’re right. Consider additional coverage for better protection.
Penalties for Non-Compliance with Auto Insurance Laws
Driving without the required insurance in Massachusetts? You’re not just risking a slap on the wrist. The penalties can be severe.
If you’re caught without insurance, you may face a fine of up to $5,000, suspension of your driver’s license, and even possible jail time. Plus, your vehicle registration could be revoked.
Here is the deal: It’s critical to ensure your insurance is up to par. Not only does it keep you protected, but it also keeps you legally compliant.
Pro Tip: Always have proof of insurance in your vehicle. Failing to present it when asked can complicate matters.
Choosing the Right Auto Insurance
So, you’re in Massachusetts and on the hunt for the right auto insurance. Confused by the endless options? You’re definitely not alone.
Choosing the best auto insurance provider doesn’t have to be overwhelming. It’s about aligning your needs with what each insurer offers and making sure you’re not overpaying for coverage you don’t need.
Evaluating Auto Insurance Policies and Coverages
Step #1: Understand your coverage needs. Do you need comprehensive coverage, or is liability enough? If your car is older, you might not need the bells and whistles that come with full coverage.
Step #2: Compare quotes from at least three different insurers. This is crucial. Prices can vary significantly for the same coverage. Don’t assume all insurers price risk the same way.
Here is the deal: Not all policies are created equal. Dig into the details and make sure you understand the limits, deductibles, and any exclusions.
Pro Tip: Always ask about discounts. Bundling your auto insurance with home insurance could save you a bundle!
The Importance of Reading and Understanding Policy Terms
Have you ever signed something only to realize you didn’t read the fine print? Auto insurance policies can be filled with jargon. But those terms matter.
Here is the deal: Pay attention to terms like “actual cash value” versus “replacement cost”. This can mean the difference between covering the full cost of a new car or just a fraction.
You wouldn’t skip reading terms for a loan. So why would you for insurance? Make sure you know what you’re buying before you sign on the dotted line.
Conclusion
And there you have it! Understanding how much auto insurance costs in Massachusetts is key to navigating the roads with peace of mind. Whether it’s by comparing rates, leveraging discounts, or choosing the right coverage, being informed is your best bet. Remember, the right policy doesn’t just protect your vehicle; it safeguards your financial future. So, buckle up and dive into your auto insurance journey with confidence!
FAQ
What is the minimum auto insurance requirement in Massachusetts?
Massachusetts requires a minimum coverage that includes bodily injury, property damage, personal injury protection, and uninsured motorist coverage.
How much does auto insurance cost in Massachusetts on average?
The average cost of auto insurance in Massachusetts is around $1,200 annually, but this can vary based on several factors.
Can my driving history affect my auto insurance rates?
Yes, a clean driving history can lower your rates, while accidents or violations may increase your premiums.
Are there discounts available for auto insurance in Massachusetts?
Many providers offer discounts for safe driving, bundling policies, and even for having certain safety features in your car.
How can I reduce my auto insurance premiums effectively?
Consider bundling insurance policies, maintaining a clean driving record, and taking advantage of discounts offered by your provider.
